Earn, Save, Invest, Grow, Borrow, Pay Interest, Repay the Loan, Die, Pay the Estate Tax
Is there a penalty for bad reporting? This week’s WSJ article entitled “The ‘Buy, Borrow and Die’ Wealth Strategy Has Become a $5 Trillion Market” makes a strong case that there should be. Here’s the lede:
Buy, borrow and die is a mantra of the rich. They love to take out loans against stock they own, so they don’t have to sell it when they want to buy other things such as mansions, yachts and movie studios.
Lots to unpack here. Start with the label. “Buy, Borrow and Die” is a misnomer. The phrase describes a supposed strategy employed by rich people to avoid capital gains tax by borrowing against their appreciated assets. That last qualifier is the key – the assets employed must have appreciated during the borrower’s ownership – otherwise there’s no tax advantage. The label also fails to capture the fact that interest must be paid on the loans as well as the estate tax implications of all this.
Put it all together and a more accurate label would be, “Earn, Save, Invest, Grow, Borrow, Pay Interest, Repay the Loan, Die, Pay the Estate Tax.” Doesn’t sound like as much fun, does it?
How big is this lending market? The headline suggests it’s $5 trillion, but that number quickly falls apart. It’s a Deloitte estimate of securities-backed credit worldwide, with only around “30% of the market is estimated by Deloitte to be in the U.S….”
So 30 percent of $5 trillion, or $1.5 trillion? That’s just 1 to 2 percent of total public securities held in the US. – hardly a widespread practice. But it’s smaller than that:
Actual borrowing may be lower because customers don’t often fully draw on their credit lines. Deloitte estimates that actual borrowing against credit lines might be closer to $1.6 trillion.
So not $5 trillion, not $1.5 trillion, but rather $500 billion. That’s one-tenth the headline number. And the introduction of “lines of credit” into the discussion seems significant. Most businesses employ lines of credit to ensure that, if they run into cash flow issues, they can stay liquid and make payroll. Are we talking about those kinds of loans here?
More on the size question. A recent paper by economists from the Michigan and Yale Law Schools looked at how prevalent borrowing was for all income classes. The key graph is below, comparing levels of debt to aggregate unrealized gains.
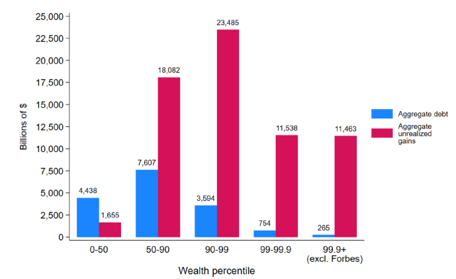
What do we learn? For the wealthiest Americans, debt is a tiny percentage of their unrealized gains, suggesting that “Buy, Borrow and Die” is more of a pithy catchphrase than a real issue requiring a legislative response. The real BBD activity is taking place in the middle-class, where families borrow against their homes to pay for college, retirement, etc.
Another challenge — the lede suggests these loans are being used for consumption purposes, as in to buy “mansions, yachts, and movie studios.”
But is borrowing money to fund the takeover of Warner Bros. to form Skydance really the same as buying a house or a boat? Since when? And why does the article cite Elon Musk specifically when he famously doesn’t have big, pricey toys?
The piece makes another claim worth exploring – that the BBD strategy is increasingly being utilized by the “less wealthy”? Seems a bit premature to show this much interest in non-billionaires. We haven’t taxed the billionaires yet, and we’re already targeting everybody else?
Even if it’s correct that the BBD strategy is spreading, what’s unclear is whether the trend is driven by a desire to avoid taxes, or because equity markets have swollen in recent years and banks are increasingly open to allowing the use of securities as collateral for loans?
Why would banks do this? Because it’s profitable. From the article – “For purebred wealth managers, such as the traditional Swiss-headquartered private banks run by families or partners for generations, Deloitte said the loans can generate 25% or 30% of annual profit.” Remember, these are real loans that require real interest payments and the eventual repayment of the principal. None of this is acknowledged in the BBD narrative.
To its credit, the article does acknowledge there are other reasons to borrow instead of selling appreciated assets, including to avoid diluting your ownership stake and to avoid the fire-sale of illiquid assets.
Both these concerns apply directly to S corporations. Selling shares of your business is difficult — there’s no ready market for closely-held businesses as there is for public companies. Moreover, diluting your ownership stake below a “controlling interest” might result not just in the loss of control, but also in the loss of value, as a minority interest in a business is worth 30-50 percent less than a controlling stake.
What to do? Borrow instead, if you can.
The “Buy, Borrow and Die” crew isn’t concerned with any of this. Their agenda is to redefine taxable income so they can tax unrealized gains. Not an easy task, but the first step is to undermine the legitimacy of the gains themselves. We used to call such gains savings and viewed them as a good thing. More savings means more capital, more investment, more jobs, and higher wages.
In the post-COVID world, however, promoting private savings is so last century. The government spends $1.40 for every dollar it collects, so it needs the dues. If collecting them means taking a normal business practice and relabeling it a tax dodge, so be it.
The “Experts” are Wrong, Part VI
This recent note from Oren Cass over at American Compass caught our eye:
Kim Clausing and I disagree on tariffs and have enjoyed debating each other a number of times, but we agree on this: There is a smarter way to tax the rich (Financial Times). Tax capital, folks. This statistic, especially, fascinated me: “Despite having the world’s most successful public companies, the US raises much less from corporate tax (about 2 per cent of GDP less) than other rich countries.”
Sure, it’s a fascinating stat. It’s also entirely bogus, as it ignores the taxes paid by 95 percent of American businesses. That’s because the US is unique in its reliance on pass-through taxation – taxing the owners of businesses directly rather than taxing the corporate intermediary. Most other countries (apart from Germany) don’t have pass-throughs.
That’s to their detriment, as the American approach has two key advantages. First, it allows for business income to be taxed at the progressive rate schedule applying to individuals. Low-income earners pay less while high-income owners pay more. Under the corporate tax, the same rate applies to billionaires and retirees alike.
Second, there’s only one layer of tax on pass-through businesses. In case you’re confused, that’s a good thing too. Taxing the same income multiple times increases the overall tax burden while creating enormous distortions between investments. It also distorts taxpayer behavior, encouraging decisions based on tax outcomes rather than what would otherwise be best for their families and businesses. Here’s George Callas from a recent post:
It has always been a principle of good tax policy that taxing income once is sound, and that both double taxation and non-taxation of income are distortive. People will argue until the End Times whether tax rates should be higher or lower, but the principle that those rates should be applied to an item of income once and only once remains. Rather than seeking to double tax family businesses, we should be pursuing corporate integration, so that corporate profits are taxed exactly once — neither zero times nor twice — either at the entity level or at the shareholder level. Rather than taxing pass-through businesses as corporations, we should be taxing corporations more like pass-throughs.2
Taxing business income once rather than twice means the US has more jobs, higher wages, and more investment than if we subjected all businesses to the corporate double tax. Here’s how EY characterized the challenge in the run-up to the fiscal cliff in 2012:
The double tax also increases the cost of investment in the corporate sector relative to the rest of the economy. This tax bias against investment in the corporate sector leads to a misallocation of capital throughout the economy. That is, capital is not allocated to its best and highest use based on economic considerations. This reduces the productive capacity of the capital stock and dampens economic growth. As noted before, the diversity of organizational forms can be seen as a useful choice for businesses to make in organizing themselves, but the impact of differential treatment should be recognized. Finally, the double tax raises the overall cost of capital in the economy, which reduces capital formation and, ultimately, living standards.
So what happens to Dr. Clausing’s stat when you add in all those pass-through taxes? The US “deficit” with Europe and other “rich” countries largely disappears. The US business sector pays just about as much as anybody else. Here’s what we wrote way back in 2019:
Measured against the overall economy, the business sector today is literally bigger than it was before the 1986 tax reform opened the door to pass through taxation. Tax Foundation numbers show that business income made up 9 percent of GDP pre-1986 (8 percent corporate income and 1 percent pass through). Today, business income makes up 11 percent of GDP (5 percent corporate and 6 percent pass through).
So the business community is larger, and pays more tax, with pass-throughs than if we returned to the bad-old days when all profitable businesses were C corporations and everybody used them as tax shelters.
That’s the lesson for today – pass-throughs are a boon to workers and the federal treasury alike. Rather than throw shade at them, we should use them as the model to build a better tax code. Next up, we’ll focus on the absolutely nutty idea that Congress should raise taxes on savings… er, capital. Sure, that will work out.
Our full “Experts Are Wrong” series is linked below:
Talking Taxes in a Truck Episode 50: The War on Pass-Throughs
Is pass-through taxation a giant loophole that steals money from the Federal government? A growing chorus Academics and journalists seem to think so. Does this new tact reflect an underlying reality or is it just the latest set of flawed talking points?
To find out, we’re joined by longtime ally George Callas, founder of the Callas Strategy Group and a DC tax policy veteran. George and Brian identify the questionable assumptions, outdated data, and misleading narratives underlying these claims. They also revisit the 1986 tax reform and explain why the rise of pass-through businesses are the solution to income inequality, not the cause of it.
Show Notes:
- Callas Strategy Group: https://georgecallas.com/
- Plucking the Golden Goose Substack: https://georgecallas.substack.com/p/welcome-to-plucking-the-golden-goose
- S-Corp on Auten & Splinter’s work: https://s-corp.org/2022/03/tax-hike-premise-takes-another-hit-debunking-saez-zucman-income-inequality-narrative/
- Washington Wire – Old Study, Same Bad Conclusions: https://s-corp.org/2026/10/old-study-same-bad-conclusions/
Two Maps, One Reality
Earlier we highlighted research showing how well the United States is doing compared to Canada. Starting in a similar place forty years ago, today’s American worker earns more and benefits from significantly higher levels of business investment. It’s a gap that is large and growing.
Today we’ve got another geography-based point to make, courtesy of the Wall Street Journal and economists Eric Zwick and Owen Zidar (both of whom spent their formative years getting called last during roll call). Their book “The Everywhere Millionaire” reviewed America’s growing ranks of job creators and discovered the American Dream is alive and well:
Across America, such business owners, we call them Everywhere Millionaires, have built extraordinary fortunes running ordinary businesses. Some launched their own ventures, working long hours and reinvesting the profits to stay afloat and grow. Others inherited a family firm and built upon the success of prior generations.
How many? Zwick and Zidar estimate there are three million of them, collectively worth more than $65 trillion. These are veterinarians, HVAC contractors, and restaurant owners. Nearly half of the nation’s $31 trillion in private business equity resides in what the authors call “tactile, Main Street industries,” businesses where something needs to be “physically moved, or get fixed, served or installed.”
The geography here is striking. The Journal’s map uses Zwick and Zidar’s data to show average pass-through income among upper-income filers on a county-by-county basis. The wealth isn’t confined to a handful of coastal enclaves. It stretches across the country, with Walker County, Alabama topping the map at an average $1.9 million.
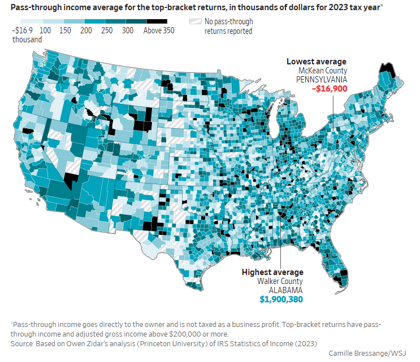
Look familiar? It should. Several years ago we asked EY to map employment at private companies across the country. The result was equally striking. Outside a relatively small number of coastal and urban areas, private companies dominate the employment base.

Combine the two maps and you get a pretty good picture of the Main Street economy. Private businesses provide the majority of jobs in this country — nearly four out of five. Our EY map shows those jobs are widely dispersed across the country, while the WSJ map shows the same goes for the wealth they generate – it’s spread across communities far removed from the usual financial and technology hubs.
The examples bear that out. Dick Portillo turned an $1,100 hot dog stand outside Chicago into a billion-dollar business. A.B. Walters built a gutter manufacturer in Natchez, Mississippi. Arch “Beaver” Aplin III built Buc-ee’s in Texas.
In recent weeks, we’ve seen a wave of proposals to raise taxes on these businesses – here, here, and here – often accompanied by the mischaracterization that the targets are primarily “law firms and hedge funds” whose income is unearned and whose wealth resides in an off-shore bank account somewhere far away.
The “Everywhere Millionaire” makes clear just how false that narrative is. The income came after decades of hard work, and the wealth is right here in the communities where we all reside and work. That’s the reality of wealth in America, and the reason voters need to reject efforts to tax wealth, these businesses, and your job into oblivion.
Old Study, Same Bad Conclusions
A decade ago, Treasury published a paper on effective tax rates that was worth a hard look. As our write-up showed, the headlines generated by the paper were not justified by its actual findings.
We’re republishing that response today because the original Treasury paper is back in the news – it’s cited in a recent NYU-Hamilton paper on pass-through businesses and two of its authors also co-authored the “Everywhere Millionaire,” a book which – as we explained the other day – is generating similarly misguided news coverage today.
New Treasury Effective Rate Study
Economists at the Department of Treasury and NBER last week released a paper reviewing the average taxes paid on business income, by entity type. We went through a similar exercise several years ago (you can read our study here), so we printed up a copy and took a look.
Here’s the headline graph:
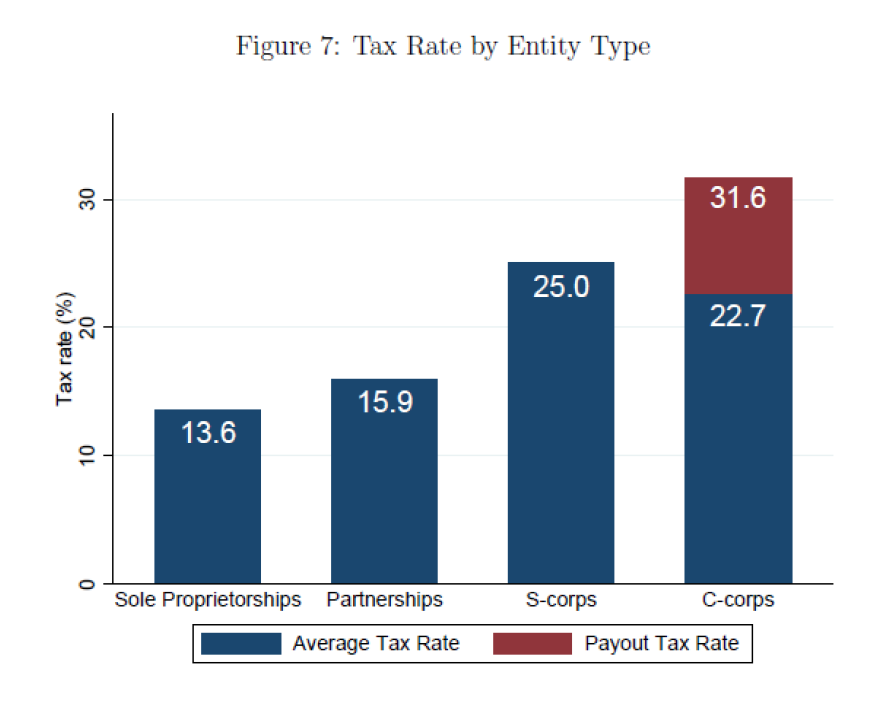 As you can see, the average tax rates for S corporations and C corporations are in the same basic range, while the averages for sole proprietorships and partnerships are significantly lower. The lower partnership average, coupled with the paper’s obvious emphasis on income inequality and the prospect of new revenues has garnered the majority of the press surrounding the paper’s release.
Below we itemize our initial thoughts regarding the substance of the paper and the quality of the estimates. But let’s face it—those items are secondary to the real point of the paper, which is to drive headlines like these:
“Pass-throughs to blame for income inequality?” — Politico
“Corporate ‘Pass-Throughs’ Have Cost the Treasury $100 Billion” – The Fiscal Times
Those headlines are based on the paper’s abstract and the general write-up, which emphasizes two basic points:
- The pass through structure contributes to income inequality; and
- Treasury would collect $100 billion more a year in revenues if C corporations were still the dominant entity type, as they were pre-1986.
The first point was summarized neatly in a Politico blog post last week:
PASS-THROUGHS TO BLAME FOR INCOME INEQUALITY? A new report by a group of Treasury Department economists and academics says the rise of business pass-throughs is a major contributor to income inequality. Pass-throughs paid an average tax rate of just 19 percent in 2011, the analysis found, compared with the 31 percent rate paid by traditional corporations. At the same time, their income accrued disproportionately – 69 percent – to the top 1 percent. “As is well-known, the top-1 percent income share doubled (from 10 percent to 20.1 percent) between 1980 and 2013,” the report said. “Less well-known is that over half (56 percent) of that increase came in the form of higher pass-through business income.”
Both Treasury and Politico have it exactly backward. Pass through taxation doesn’t add to “income inequality.” C corporation tax treatment masks it. This is something we have written about in the past.
Take Warren Buffett. He owns a large share of Berkshire Hathaway. That corporation pays no dividends and Buffett never sells any stock, so if one was just looking at the tax rolls, Buffett’s reported income is relatively low despite the fact that he’s one of the richest men on the planet. All his income is effectively hidden within Berkshire’s corporate structure. Treasury touches on this dynamic in a footnote at the bottom of page 2:
Note that this evidence may seem to suggest at first glance that at least a portion (e.g., perhaps 56% x 35% = 20%) of the rise in the top-1% income share could reflect merely a change in how business income is reported on Form 1040 returns: before annual business income taxes (as pass-through income subject to ordinary individual income taxes) rather than after annual business income taxes (as post-corporate-income-tax dividends or capital gains distributions).
Figure 2 at the back of the paper helps illustrate this dynamic.
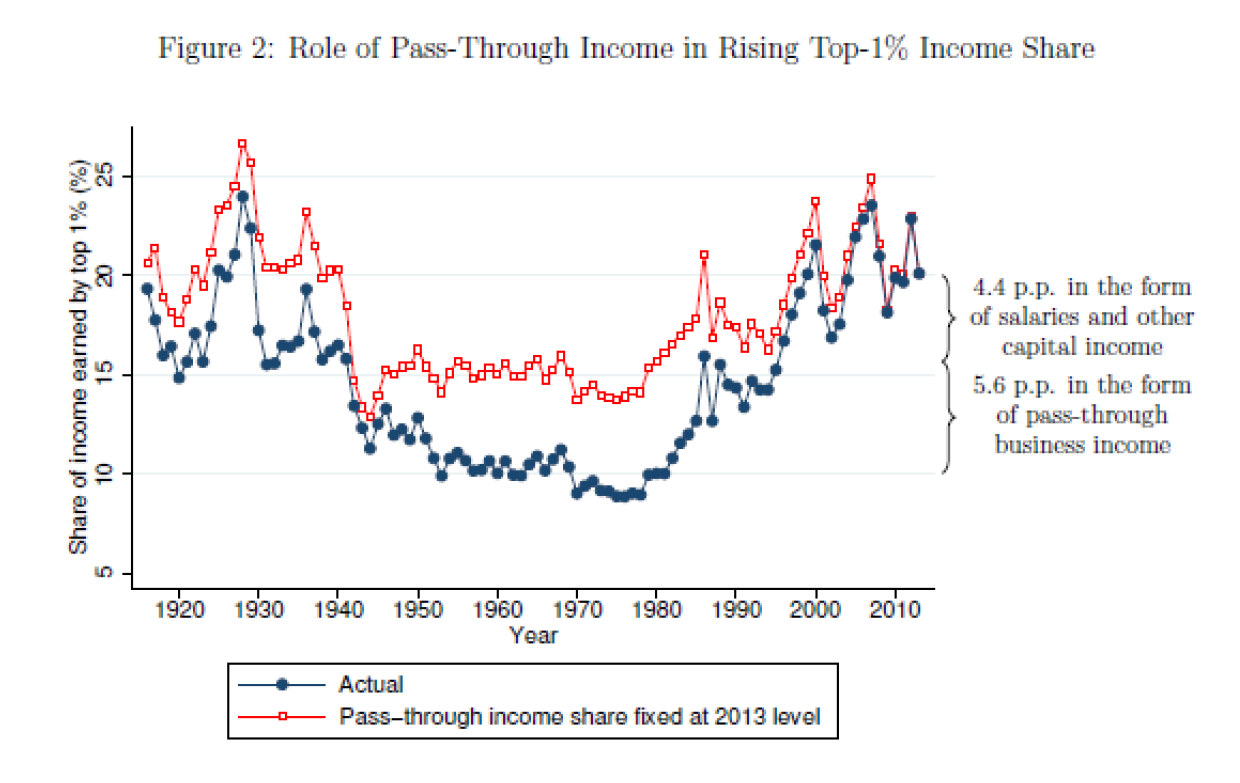
The blue line shows the rise of income inequality, thanks to data from Piketty and Saez. The red line shows how much less inequality would have risen if businesses back in 1980 were taxed as businesses in 2013 – i.e. all that income showed up on the individual tax forms rather than the corporate ones. Lesson: C corporation taxation masks income inequality.
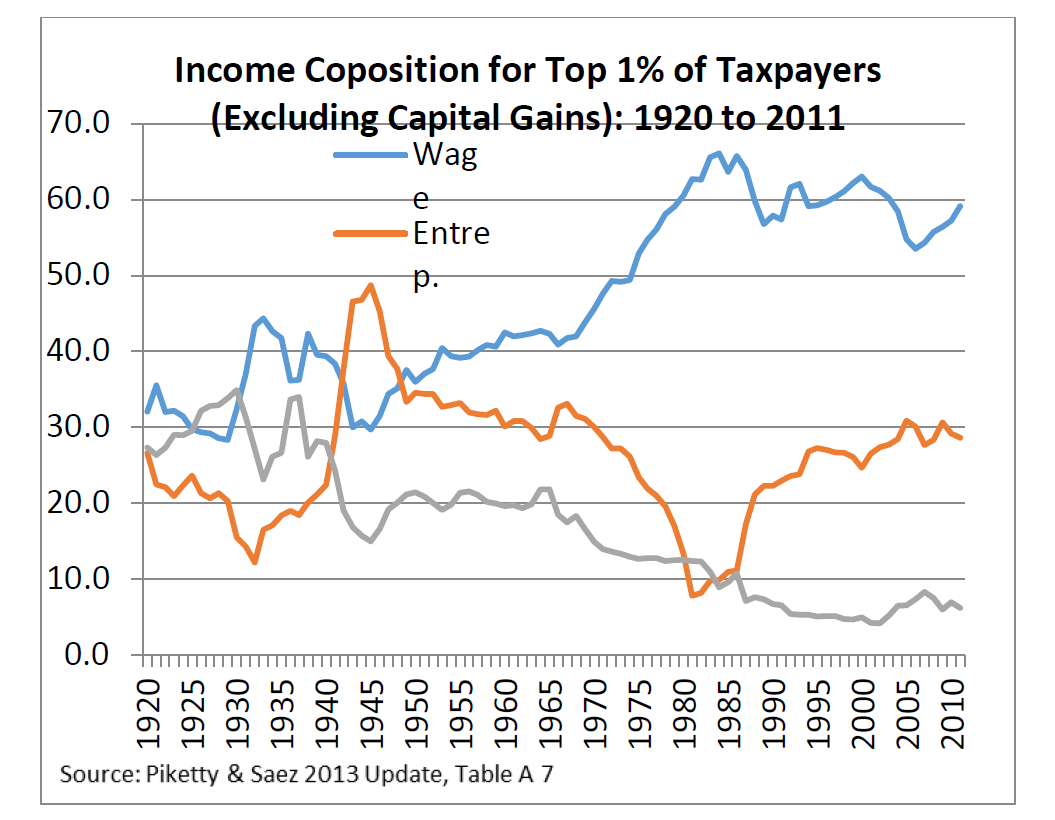
Here’s the underlying data from Piketty and Saez. Notice how the “entrepreneurship” income bottoms out right when Ronald Reagan began cutting marginal rates on individual and pass through businesses in 1981? A large part of the perceived growth in upper incomes is really just an accounting shift from corporate to pass through tax reporting.
The second assertion is that Treasury would collect $100 billion per year in revenues if C corporations were still the dominant business type. Here’s the study:
If pass-through activity had remained at 1980’s low level, strong but straightforward assumptions imply that the 2011 average U.S. tax rate on total U.S. business income would have been 28% rather than 24%, and tax revenue would have been at least $100 billion higher.
We’ve pointed out in the past that the migration of businesses from the inefficient corporate tax to the more efficient (and equitable) pass through structure has been a boon to the American economy and workers. As our 2011 EY study made clear, there are more businesses, higher levels of capital, and more jobs because of pass through taxation.
Measured against the overall economy, the business sector today is literally bigger than it was before the 1986 tax reform opened the door to pass through taxation. Tax Foundation numbers show that business income made up 9 percent of GDP pre-1986 (8 percent corporate income and 1 percent pass through). Today, business income makes up 11 percent of GDP (5 percent corporate and 6 percent pass through).
So if you are going to revert back to pre-1986 shares of business income, don’t you need to revert to the smaller economic footprint as well? That would mean expanding the application of the corporate tax to more business income, but also shrinking the total business tax base by about 20 percent. That adjustment would effectively wipe out any prospective revenue gain. Add in today’s higher tax rates on pass through businesses and it is possible the Treasury approach would lose revenue.
The study recognizes the inherent weakness of the $100 billion estimate:
We stress that this exercise is not a projection for the likely effects on tax revenue from business tax reform. It is mechanical and assumes no behavioral responses, but has the advantage of being transparent.
Transparent it might be but, unfortunately, this nuance was lost to the popular press. Beyond these two key points, here are other thoughts regarding the report:
- The new study uses 2011 filings and tax rules, so it misses the sharp rate hike on pass through businesses that took effect in 2013. That change alone should dramatically raise the resulting effective rates on S corporations and partnerships.
- Despite employing pre-2013 rates, the study finds that S corporations pay the highest average tax on their income (25 percent vs. 22 percent for C corporations) before shareholder-level taxes are factored in.
- The study then assumes shareholder-level taxes add another 9 percentage points to the C corporation average rate, but that assumption is based on economic literature from 2004 rather than tax collections from 2011. It also employs heroic assumptions about the composition of corporate distributions (Footnote 16). Definitely worth further review.
- For partnerships, the study fails to differentiate between active business income and investment income, which is obviously taxed at lower rates. The study notes that 70 percent of partnerships are “finance and holding companies.” To the extent these partnerships are investing in C corporations whose income is already taxed at the entity level, it makes sense that their effective tax rate would be lower than the top statutory rate. Perhaps this partnership income should be included in the C corporation bucket, since they are C corporation shareholders?
- The study attributes twenty percent of the partnership income to “Unidentified TIN type” and “Unidentified EIN.” It then appears to assume this unidentified income was taxed at a blend of the two lowest applicable rates, resulting in an even lower average rate for partnerships. As with the C corporation shareholder assumptions, definitely worth a further look.
These are just our initial reactions to the Treasury report. We will have more to say in the future. The report was written by serious people and it deserves a serious response. But the news cycle doesn’t follow the academic calendar, and the study’s emphasis on income inequality and revenue gains are driving numerous news stories today. So it was important to remind our members that this study is not the last word in pass through taxation.