Setting the Record Straight
This week the Treasury Department took the important step of finalizing its Corporate Transparency Act rules. While the move was cheered by the broader Main Street business community, a small contingent on social media has been spinning it as a “win for criminals.”
For example, here’s the start of a multi-part thread from former Congressman Tom Malinowski that’s laden with falsehoods:

The reality is that the CTA, as designed, does little to catch actual criminals, and instead penalizes millions of law-abiding business owners instead. Real criminals don’t self-report. Drug traffickers, money launderers, and arms dealers won’t voluntarily submit accurate beneficial ownership information. As we’ve said before, can you imagine Tony Soprano sitting in his kitchen filling out forms identifying the senior members of his crime family and which enterprises they benefit from?
Instead, the burden will fall on honest business owners navigating a massive, unwieldy database. With 30+ million business entities reporting multiple beneficial owners each, that’s 100+ million records for law enforcement to sift through without any targeted leads or probable cause. Finding actual criminals in that haystack is practically impossible. Add in the complexity of compliance and steep penalties, and the CTA looks less like a tool to catch criminals and more like a compliance nightmare.
The CTA was also never about tax administration. It’s a blanket reporting requirement imposed on every business owner without individualized suspicion, essentially a mass privacy invasion. That’s constitutionally problematic and practically ineffective. Treasury’s exemption for certain entities is appropriate and overdue. Law-abiding business owners shouldn’t have to surrender their privacy to a federal database simply because they formed an entity.
S-Corp and its allies have fought the CTA since its inception more than five years ago. As dubious claims about the CTA continue circulating online, we’re compiling this resource guide so you can fact-check the next misleading thread you encounter. The evidence speaks for itself, so be sure to share these materials when you see false claims.
CTA Resources
- Complete Database: S-Corp Wires / CTA Alerts
- Joint Trade Association Letters
- Repealing Big Brother Overreach Act (HR 425 / S 100)
- NFIB: CTA Landing Page
- NSBA: CTA News & Status
- NSBA v Yellen
- Texas Top Copy Shop, Et. Al v Blanche
- FinCEN Final Rule
Revisiting the Myth of Corporate Decline
In 2019 we dismantled the claim that the corporate sector was withering away and that those pesky pass-throughs were to blame. Seven years on, the numbers have only made our case stronger.
Corporate profits hit $4.42 trillion last quarter on an annualized basis, while their after-tax profits reached 12.4 percent of GDP, the second-highest reading in decades. C corps aren’t going away; they are consolidating and getting larger.
Which is why we continue to focus on the need for balance between public companies and private ones, and how the tax code’s treatment of each determines whether Main Street can stay competitive with Wall Street.
—
The Myth of Corporate Decline
July 26, 2019
The visual economist issued another great chart last month, this time showing the largest public companies by market cap.
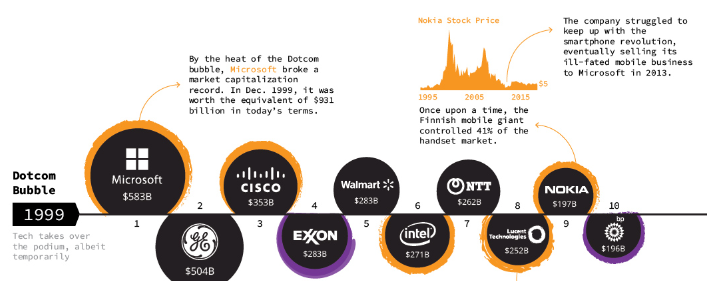
Our first reaction is, wait, Microsoft is number one? When did that happen? All the focus on FAANG stocks (Facebook, Amazon, Apple, Netflix and Google) and stodgy old Microsoft is bigger? Go figure.
Our second reaction is “Gee Grandmother, what big market caps you have.” These companies are huge! And that’s not limited to the ten companies illustrated here. Measured against GDP, the market cap of all public companies in the US has tripled since 1986.
The irony is that this growth came at a time when we were warned repeatedly that the corporate sector was shrinking and it’s all the fault of the 1986 tax reform act and those pesky pass-through businesses. Here’s a representative example from the Tax Foundation from 2015:
The U.S. loses about 60,000 corporations per year and has lost about 1 million corporations since the Tax Reform Act of 1986.
Over time, more businesses have structured themselves as “pass-through” entities. This allows profits to be passed through to owners and taxed at individual tax rates that are often lower than the corporate tax rate and eliminates double taxation for shareholders.
More than 60 percent of U.S. business profits are now taxed under the individual income tax code rather than the corporate tax code, which explains why the U.S. collects a relatively small amount of tax revenue from corporations despite having the developed world’s highest corporate tax rate.
Outside of taxation, the traditional corporate form often provides the most efficient business structure for large-scale projects and investments. Excessive corporate taxation and the subsequent decline of the corporate sector artificially limits this important aspect of the economy.
The U.S. should do what the rest of the developed world has done: reduce the corporate tax rate, integrate the corporate and shareholder taxes to avoid double taxation, and limit corporate taxation to profits earned domestically.
Just for the record, in 2015 the top rate on pass-through businesses was higher than the top rate for C corporations, but we digress — If the 1986 tax reform spelled the demise of C corporations, how come the smart money continues to pour into them?
The simple fact is the “decline of the corporate sector” narrative was a myth no matter how you measure it. Corporate tax receipts were 1.4 percent of GDP prior the 1986 tax reform; they were 1.5 percent of GDP prior to the 2017 tax reform. Corporate taxes paid as a percent of total government receipts were 8.2 percent in 1986; they were 9.0 percent in 2017.
So the C verses S dichotomy painted by the Tax Foundation and others is the wrong way to frame the debate over how to best tax businesses. What’s the right way? Here are some thoughts:
- The real balancing act is not between pass-through businesses and C corporations, but between public companies and private ones. The decline in C corporation numbers is dominated by private companies either moving into the pass-through space or being gobbled up by public companies. It’s true the number of public companies listed on the US exchanges shrunk by half over the last two decades, but it’s only a few thousand companies and the overall growth of the remaining market cap indicates that what we’re seeing is consolidation, not decline.
- The dramatic increase tax exempt shareholders is likely responsible for some of this growth. In the 1960s, four out of five C corporation shareholders was fully taxable. Today, it’s just one out of four. This growth in tax exempt or advantaged investment increased the pool of capital available to public companies over the past fifty years even as it sharply reduced their effective tax rates.
- The rise of tax exempt shareholders has also given public companies a significant advantage over private C corporations. Unlike public companies, private companies are largely limited to rewarding their shareholders by paying dividends, and those dividends are usually – and in the case of S corporations, always – paid to shareholders who actually pay taxes. The double tax lies more heavily on private companies.
- Tax reform will push more business income into the double tax. Barro-Furmanestimate 19 percent of pass-through income will migrate into the lower, 21-percent corporate rate. Wharton estimates its 18 percent. Some of this shift may come from conversions of existing companies, but much of it will be in the form of increased consolidation, either through acquisitions (Berkshire Hathaway) or by public companies taking market share from existing private businesses (Amazon). Bottom line: More business income will be subject to the harmful, distortive double tax in coming years.
The common perception that the 1986 tax reform favored pass-through businesses ignores just how tax-disadvantaged pass-through businesses were prior to 1986. The top tax rate imposed on pass-through income was 70 percent prior to the Reagan revolution. The top rate on C corporations was 46 percent. As result, nearly all business income prior to 1986 was reported by C corporations, not pass-throughs.
But pass-through taxation is the correct way to tax business income! The tax code should tax all business income once, when it is earned, and at reasonable rates. S corporations for everybody is our mantra. Re-read the policy prescriptions of the Tax Foundation paper:
The U.S. should do what the rest of the developed world has done: reduce the corporate tax rate, integrate the corporate and shareholder taxes to avoid double taxation, and limit corporate taxation to profits earned domestically.
We agree – double taxation is the wrong way to tax business income and eliminating it should be the focus of tax policy moving forward, not promoting myths about corporate-tax-base erosion.
Backdoor BOI
Yesterday’s final rule eliminating BOI reporting requirements for US persons or entities is a big win, but the fight over the Corporate Transparency Act is far from settled. Congress is considering legislation that would provide permanent relief for Main Street, while the Supreme Court will decide soon whether to hear a constitutional challenge to the law.
On the other hand, proponents of this unprecedented information grab have not abandoned their cause and appear to be pursuing beneficial ownership reporting one industry at a time. For now, they’ve turned their attention to health care.
The Senate HELP Committee recently advanced the Patients Deserve Price Tags Act, legislation intended to increase transparency in health care pricing. Buried within the bill, however, is a mandate that looks familiar to anybody who has followed the Corporate Transparency Act debate.
Under Section 6 of the committee-passed bill, every health insurer offering coverage in the individual or group market would be required to submit to federal and state regulators, and make available to the public, the following:
“the name and business address of each person or entity that, with respect to such plan or coverage… has an ownership or investment interest; has a controlling interest; is a management services organization; or is a significant equity investor.”
The disclosure would begin one year after enactment, be refreshed every quarter whenever the information changes, and be backed by civil monetary penalties of up to $300 per covered individual per day or $10 million, whichever is less.
Nor does the mandate appear to be limited to insurers. Identical disclosure language is sprinkled throughout the bill and applies to hospitals, clinical laboratories, imaging providers, and surgical centers, each of which would be required to post its ownership roster. So even as we make progress rolling back the CTA at the administration level, the Senate is attempting to recreate the law, industry by industry.
In one important respect this version goes further than the CTA ever did. Ownership information reported under the CTA at least sat in a government database subject to access restrictions. Here, the names and addresses of owners and investors would be published for anyone to see.
Supporters will argue this is simply another health care transparency measure. But requiring health care operators to publicly identify their owners, investors, and management goes well beyond helping consumers compare prices or understand their coverage. An ownership roster tells a patient nothing about what an MRI costs.
Fortunately this proposal still has a long way to go. The ownership disclosure language cleared the Senate HELP Committee, but the House version ditches the provision, meaning this issue is likely headed for a conference fight.
Main Street businesses have already made clear where they stand on the CTA. Congress should reject this latest attempt to revive beneficial ownership reporting through the back door.
Big Win on CTA!
Good news for the lazy days of summer! The Trump Treasury Department has finalized its revised beneficial ownership information (BOI) reporting rule and committed to permanently deleting the sensitive personal data prematurely collected from millions of U.S. business owners. This is a significant victory for Main Street and the latest chapter in our years-long fight against the Corporate Transparency Act.
Treasury estimates the rule will generate $9 billion in annual compliance savings. That’s a huge sum, but it doesn’t account for the funds Main Street businesses have already spent trying to decipher this unnecessary rule. This reply to S-Corp ally Carol Roth’s tweet summed up the frustration among business owners perfectly:

A big headline here is the database purge. FinCEN announced it will delete all BOI information previously collected from U.S. owners and entities – by our estimate that’s 15 million entities and who knows how many tens of millions of individuals. The move reflects a recognition of what we’ve argued from the start: requiring millions of law-abiding business owners to disclose their personal information serves no meaningful law enforcement purpose and exposes them to unnecessary costs and privacy risks.
Treasury’s action today is welcome news, but it’s not the end of the fight. The rule makes permanent the interim guidance issued last March, which narrowed reporting to foreign entities only. But that relief exists at the discretion of the White House and can be unwound by a future administration. That’s why the push for a permanent fix through a statutory repeal or a court order remains at the top of the to-do list.
For now, however, we’re celebrating the big “W.” Thanks to Treasury for getting the regs right, and we will continue to fight for permanent relief on behalf of the Main Street business community.
Who You Calling Progressive?
One of the of the more entertaining aspects of today’s election news is the insistence on branding Abdul El-Sayed, the hard-left winner of yesterday’s Michigan Democratic Senate primary, a mere “progressive.” Meanwhile, his more traditionally progressive opponent, Haley Stevens, has been recast as a “moderate.” More moderate than El-Sayed, certainly, but…
With that as a conversation starter, here are some take-aways from yesterday’s remarkable primary election.
The Goal Posts Have Shifted
The most obvious take-away is how the goal posts have shifted on what counts as “mainstream” these days. The New Republic published this eye-opening piece just yesterday about how Senator John Fetterman (D-PA) is now on the outside looking in if Democrats win the Senate:
Fetterman noted that he agrees with the Democrats on the vast majority of policy issues. But based on his public comments, the senator seems fixated on two particular matters: Israeli-Palestinian policy and the progressive-socialist left. And on those two matters, the divide between Fetterman and the Democratic Party is huge and growing. The Democratic left that Fetterman goes on Fox News to bash is surging in numbers and power—in no small part because of the status quo that Fetterman has done much to uphold. Antipathy toward Israel has expanded from progressive politicians to even average Democratic voters.
Senator Fetterman is no longer a Democrat in good standing because he isn’t a socialist and supports Israel?
The Polls are Still Wrong
Meanwhile, the polls continue to be unreliable. El-Sayed won yesterday, but not by nearly as much as predicted. Granted, polling in primaries is difficult because turnout varies significantly. That’s compounded by states with open primaries, like Michigan, where Independents and even Republicans can switch over and vote in the Democratic race. That said, this is ridiculous:
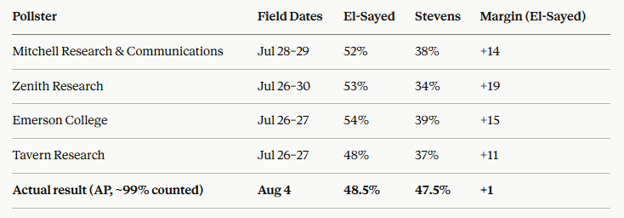
Republicans like to complain that polling is historically biased against them, but in the post-COVID world, polling seems to be wrong in all directions. The Red Wave predicted by nearly all the polls in 2022 never materialized even as Trump has consistently out-performed in his races.
Our friends at the Winston Group have a new video explaining what’s wrong with polling these days – worth a watch.
Count on Divided Government
El-Sayed’s victory yesterday all but assures Republicans will retain control of the Senate next year. The odds of Mike Rogers winning Michigan just shot up sharply and Susan Collins (remember that other progressive, Graham Platner?) is going to win Maine. That would force Democrats to run the table of remaining toss-up races — Alaska, Georgia, Iowa, New Hampshire, Ohio and Texas — to get to 51 votes. Not gonna happen. And if it does, as the New Republic frets, what do they do about Fetterman?
Implications for Tax Policy
Which brings us to tax policy. It’s hard to describe the future direction of tax policy without sounding like Chicken Little, but there you have it.
On the left, the focus used to be on raising revenue to finance an expanded vision of government. Now, they resemble a cudgel crafted to punish anybody they don’t like. That’s largely billionaires and public corporations for now, but the list is sure to grow. Anybody in the wrong industry or on the wrong side of a revolving number of political questions can expect to be targeted.
On the right, the battle is between old school supply-siders, a few remaining traditional deficits hawks, and a new breed of quasi-populists who think they invented mercantilism. Groups like American Compass support raising tax rates on wealthy individuals and corporations, imposing high tariffs that largely fall on the working class, and growing government so they can “invest” in new industries and technologies. How they have the expertise to successfully pick those industries and investments is not exactly clear.
Largely missing from the discussion are people who just want to fund necessary but limited government functions while doing as little harm to the economy as possible.
Conclusion
All this political and policy chaos comes at a moment when our fiscal house is in its worst shape ever. Annual deficits are huge and growing, our national debt is well over 100 percent of GDP, and Social Security is going broke in five years. That all these red flags are flying when the economy is robust and unemployment is low is even more worrisome. What happens with the next recession? Where’s the safety-net then?
Something has to give, and as yesterday’s results make clear, you only need a small minority of Americans to make a big difference. As Reason magazine has pointed out, every over-educated, downwardly mobile voter in Michigan showed up yesterday to support El-Sayed. Will Main Street show up in force this November to counteract them? It’s just our economic future we’re talking about here.