Australian CbC Reporting and S-Corps, Continued
The S Corporation Association today sent a letter to the Australian Tax Office (ATO) building on our ongoing discussions regarding how Australia’s proposed Country-by-Country (CbC) reporting rules could affect S corporations operating in the United States.
By way of background, Australia is in the process of implementing new CbC reporting requirements they say will provide greater transparency for multinational companies doing business in the country. These rules would apply to sizable companies doing business in Australia, including large S corporations.
S corporations are pass-through entities, however, taxed at the shareholder rather than the entity level, and therefore do not pay corporate income taxes or maintain entity-level tax information that the Australian rules are designed to capture.
As the letter notes:
Subjecting S corporations to the CbC reporting would fail to produce the information the rules are designed to collect – namely, whether large businesses operating in Australia are appropriately contributing to Australia’s tax base. Instead, the reporting would provide a distorted view of tax compliance by reporting income but no tax payments, while also raising significant shareholder privacy concerns.
S-Corp isn’t alone in raising concerns. Other companies have voiced similar warnings about the unintended consequences of Australia’s approach, citing both competitive and privacy risks. Together, these comments underscore the debate over CbC reporting is not about opposing transparency; instead, it’s about ensuring such efforts are designed to collect meaningful, accurate information without undermining legitimate privacy protections.
The letter also highlights the structural safeguards embedded in U.S. law that prevent S corporations from being used as vehicles for tax avoidance. Only individuals (not corporations or partnerships) can own S corporation shares while ownership is subject to a single class of stock rule that ensures all shareholders are treated proportionally. As the letter points out, “these unique rules ensure that, should the ATO grant an exemption for S corporations from the CbC reporting regime, it would not open the door to avoidance strategies.”
To address these concerns, the ATO should exempt S corporations from the CbC requirements entirely. At a minimum, they should limit reporting to business operations within Australia only. Such a targeted approach would avoid the misperception that S corporations pay no tax and protect shareholder privacy, while providing Australian authorities with meaningful information on income and activity within their jurisdiction.
We’ll continue working with Australian tax officials and other international stakeholders to ensure that S corporations are treated appropriately under foreign transparency regimes.
Webinar Recap: Delivering for Main Street
The One Big Beautiful Bill is delivering real benefits for millions of small and family-owned businesses, but how many taxpayers know they benefitted, and how should Main Street advocates best communicate those benefits?
That was the central focus of our latest webinar featuring longtime allies David Winston and Myra Miller of The Winston Group, who walked through fresh national and Georgia-specific survey results focused on the new tax bill.
Key takeaways included:
- Taxpayers strongly support the tax bill, but only when they understand how they benefit from its provisions. Main Street advocates need to discuss the specifics of the bill and avoid assuming their audience knows they saw tax relief.
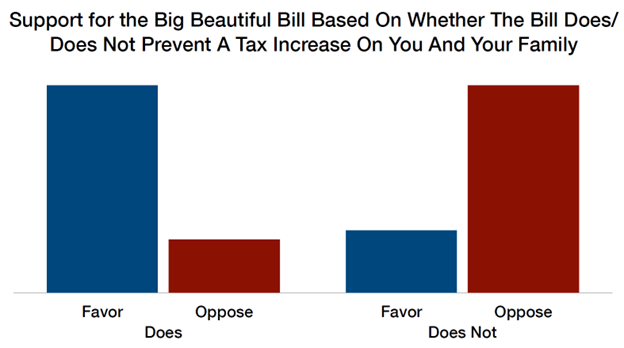
- Taxpayers responded most positively to the three core Main Street provisions – permanent Section 199A, preserving SALT parity, and avoiding rate hikes.
- Finally, while taxpayers are not convinced that inflation is under control, they do fear raising taxes on Main Street businesses would result in higher prices, as the cost of those tax hikes would be passed on to consumers.
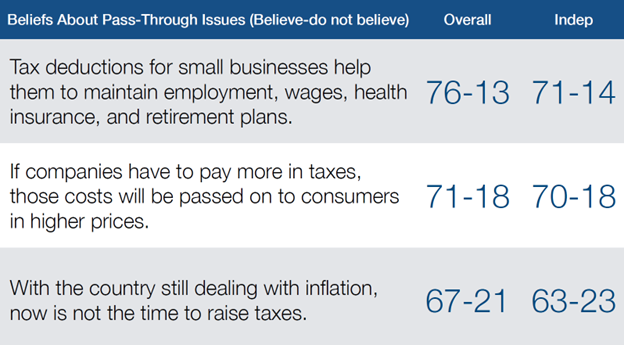
So the big tax bill might be signed into law, but the debate over its merits has only begun. For Main Street advocates, you can’t assume business owners know they got a tax cut – you have to be specific and make the case. That’s exactly what we intend to do at S-Corp: highlight how the One Big Beautiful Bill is helping Main Street businesses invest, hire, and grow.
<A full recording of the webinar is available here>
Talking Taxes in a Truck Episode 44: The Shutdown Edition
Joe Lieber is a founder and co-managing partner of Capitol Policy Partners, a veteran DC insider and a longtime friend of the TTT podcast. With a government shutdown all but inevitable at this point, we asked Joe how long we can expect this fight to play out, whether a grand bargain is in the offing, and the implications of a prolonged funding lapse. Later we get into the prospects of a year-end tax package and whether businesses should or should not expect a second reconciliation bill (Too Big, Too Beautiful?).
This episode of the Talking Taxes in a Truck Podcast was recorded on September 30, 2025.
Tax Cuts Don’t Sell Themselves
In Washington, passing major tax legislation is hard. Convincing Americans they actually benefited from it is often even harder.
That’s the central argument David Winston – founder of the polling and research firm The Winston Group and a longtime S-Corp ally – makes in a recent Roll Call op-ed, and it rings especially true for Main Street employers. Despite the significance of the One Big Beautiful Bill (now being referred to as the “Working Families Tax Cut”), public perception hasn’t quite caught up to reality. As David notes, tax cuts don’t often get the credit they deserve, and people may notice their tax bills have shrunk, but they rarely attribute that to congressional action:
These across-the-board tax cuts were going to expire at the end of this year, and if that had happened, most people in the country would have seen their taxes go up. Yet sadly, a kind of cynicism has settled over many voters who remain unconvinced of almost anything they hear from politicians and the media these days.
This is hardly a new phenomenon. Following the 2017 tax reform bill, the data clearly showed that most taxpayers received tax relief, but research by The Winston Group showed only about a third of Americans believed they had. And that was despite clear, measurable savings. Likewise, our EY study found that tax relief for pass-through businesses (particularly 199A) translates into higher wages, more jobs, and increased investment. In short, the policies worked, but the politics and messaging lagged.
The same dynamic is at play today. The Working Families Tax Cut delivers the most significant set of Main Street-focused tax reforms in over a decade. Permanent extension of Section 199A (which directly supports 2.6 million American jobs), higher estate tax exemptions (critical to ensuring future generations doesn’t have to buy the whole business back from the government), R&E expensing (which prevents massive, unexpected tax bills), and other pro-growth policies all go straight to the heart of how family-owned companies grow and transition. These provisions also help ensure parity between pass-throughs and their publicly-owned corporate competitors, which pay far lower rates, and ultimately drive down costs for consumers. Yet, as David points out, voters’ default assumption is that their taxes are going up, not down.
That creates a messaging gap and a political risk. If people don’t know they got a tax cut, they won’t reward the policymakers who made it happen. Worse, they may be swayed by opponents who characterize the reforms as giveaways to someone else. This is exactly what happened post-2017 — despite widespread tax relief, the reforms never enjoyed majority public support.
The solution, as David argues, is sustained follow-through. That means telling the stories of Main Street businesses that are using the tax relief to hire more workers, reinvest in plant and equipment, and continuing their community support. Those are the stories S-Corp and its Main Street allies will be telling in the months and years ahead, and we encourage the rest of the business community to do the same.
In the end, the success of the reconciliation package will hinge on whether Americans fully understand how it benefits them.
Talking Taxes in a Truck Episode 43: EY’s Dianne Mehany Decodes the Big Beautiful Bill
With the One Big Beautiful Bill Act (Working Families Tax Cut?) officially the law of the land, how are private companies responding? And where does tax policy go from here? We invited EY Private National Tax Leader Dianne Mehany to the podcast to discuss those questions and more. Dianne breaks down the key provisions and how they’re playing with clients (199A, SALT, estate tax). Later we discuss the legislative outlook, new country-by-country reporting requirements, and the advantages of a Ford F-150 over Uber.