Blood from a Stone
While most people were trying to file their taxes last month, Senator Elizabeth Warren was busy trying to raise them. Her reintroduced Ultra-Millionaire Tax Act of 2026 would impose a 2-percent annual levy on individual net worth above $50 million, a 3-percent rate on billionaires, and generate what its proponents claim will be over $6 trillion. That estimate is the economist equivalent of drawing blood from a stone – it doesn’t exist and it shouldn’t be taken seriously.
Warren’s latest proposal also includes a 40 percent “exit tax” on the net worth of any American worth more than $50 million who renounces their citizenship. The message, delivered with all the subtlety of Sonny locking the bar door in A Bronx Tale, is unmistakable: “now you can’t leave.” Setting aside the enforcement and constitutional issues, we would again point out that forcing people to stay is hardly the foundation of a healthy relationship. It is what totalitarian governments do, not democracies.
Back to the revenue estimate, the $6.2 trillion figure comes from Berkeley economists Emmanuel Saez and Gabriel Zucman, the same duo who have animated every version of this wealth tax since 2019 (and whose wildly inaccurate claims we’ve covered for even longer).
In terms of methodology, they start with the Forbes real-time billionaire list, assume an annual wealth growth rate of 4 percent, slap on an arbitrary 15 percent haircut for “evasion and avoidance,” and call it a day. If that approach sounds familiar, it should. Saez used the same “back of the envelope” approach for his estimate of the California wealth tax initiative.
These rough estimates are a poor substitute for reality. They ignore any behavioral responses and assume the economic landscape will look the same after the tax as before. In this fantasy world, the federal government seizes two to three percent of high-net-worth capital every year but nothing changes – the capital remains in place, businesses remain structured as they are now, and entrepreneurs keep building wealth at the same rate. Sure.
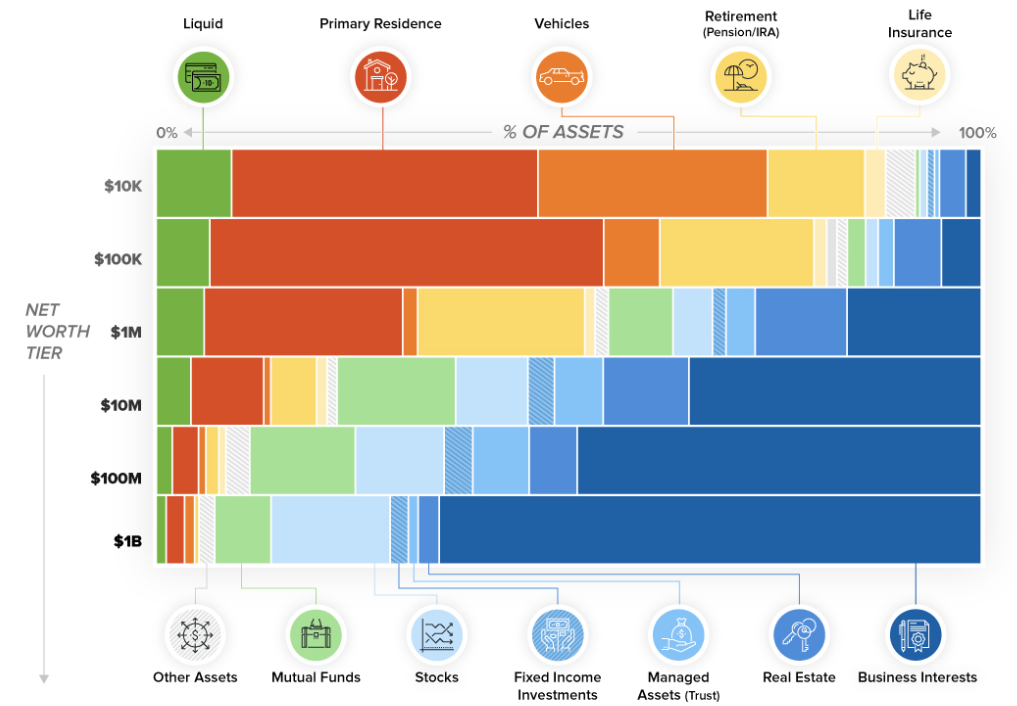
One challenge among many — most of the assets held by wealthier Americans are not sitting in a brokerage account, waiting to be liquidated. Rather, they are in the form of equity in enterprises that, cumulatively, employ millions of people. The dark blue area in this Visual Capitalist chart reflects illiquid business assets subject to tax under the Warren bill. In effect, the federal government becomes a preferred shareholder in every one of those enterprises, extracting an annual dividend whether the business makes money or not.
For example, the Warren tax would impose an annual $3 million tax bill on the owner of a $200 million manufacturing operation. This comes on top of income taxes, so if the company earns a 6 percent return on its assets – a very respectable return – then the income tax would take about 2 percent and the wealth tax another 1.5 percent.
That leaves the owner with an after-tax return of just 2.5 percent (not respectable) and wondering where else they can invest their capital. The “just two cents” framing Warren deploys to sell her tax is really a 62 percent confiscatory tax, and that’s under the best of circumstances.
What if the company loses money? How does the tax work then? It’s simple — the owner still owes $3 million. Without any income, they have to dip into their savings or borrow against the (declining) value of the business. To be clear, this is not a public company where shares are easy to value and sell. Borrowing for closely-held businesses is much more involved. And there are limits — what if the company is already fully leveraged?
Now take the negative effects this tax has on this one company and multiply them across the 260,000 households Warren’s bill targets. It’s easy to see the behavioral response will not be negligible but very, very robust. Just ask California, New York, Washington, the UK, Spain, Norway, and other jurisdictions experiencing rapid outmigration.
Warren’s bill will not pass this Congress, but the proposal does not have to become law to do damage. As with the California initiative, the threat alone accelerates restructuring, departures, and capital flight. In the end, the disruption to business and investment will be higher than expected, and the revenue raised will be lower than advertised. As the adage goes, you can’t draw blood from a stone.
Greater Fool Markets
In economics, the “Greater Fool” theory holds that investors buy overpriced assets expecting others will pay more for them later. So a stock or real estate bubble will continue until the proverbial “last fool” jumps in, at which point there’s nobody left to keep the bubble going and it bursts.
We need an analogous theory for tax policy these days. States like California, New York, and Washington continue to raise taxes and otherwise create an environment that is hostile to investment and entrepreneurship. The result has been an unprecedented flight of taxpayers and capital out of those states:

So how are the policymakers responding? They’re raising taxes further, imposing an even heavier burden on the remaining tax base. At some point, the last viable taxpayer will depart and the state’s fiscal health, just like a market bubble, will burst.
Businesses and investors residing in low tax states need to pay attention to all this, since the “Greater Fool” theory of taxation isn’t just a state-level challenge; it’s federal too. Despite the fact that today’s federal tax revenues are above historic levels and the tax code is more progressive (as in, the rich pay more) than at any time in the last 60 years, some folks want to raise taxes dramatically.

As the CBO noted in its last Budget Outlook, “Measured as a percentage of GDP, outlays exceed their 50-year average by a widening margin from 2026 to 2036 in CBO’s projections. Revenues rise just above their 50-year average in 2026 and then change little, remaining above that historical average throughout the 10-year period.”
Meanwhile the rich are paying a large and increasing share of those taxes. Here’s the Tax Foundation on that point:
 So that’s good news – we’re getting more revenue from a more progressive code. How are some policymakers responding? They’re calling for even higher taxes, including taxes on wealth, taxes on high incomes, taxes on unrealized gains, taxes on loans, taxes on estates. The list goes on and on.
Returning to our Greater Fool analogy, the challenge is taxpayers and capital can leave a country too, not just states. Such migration might be a little more involved in some cases, but capital flight is a very real thing, and its economic consequences are harmful for the country on the losing end.
The good news is we haven’t fully crossed that line yet. America remains one of the top destinations in the world for millionaire migration, continuing to attract investors, entrepreneurs, and capital from abroad. But that standing can be reversed surprisingly quickly when policies move in the wrong direction.

For example, the UK is estimated to have shed some 27,000 high-net-worth individuals in 2024 and 2025 – the largest outflow of any country during that period – largely in response to new taxes on inheritances and investment income. It’s a similar story in Spain, Norway, and France, each of which have implemented some form of a wealth tax in recent years.
Keep in mind that taxpayer migration isn’t the only way capital avoids excessive taxation. It’s much easier for taxpayers to simply invest in other countries or in foreign companies. Sure, they have to pay the domestic tax on any returns, but at least the investment is in a pro-growth environment.
And what about capital that never comes here at all? Have a great idea? Plant it someplace else, so that when it grows, it skips the confiscatory taxes. For foreign based investors, they can look elsewhere, someplace with better rates and a more business-friendly environment.
Investing in assets that are well above their intrinsic value is a fool’s errand. So is taxing investment and capital at rates above what taxpayers are willing to pay. As our economist friends have demonstrated, federal tax rates already hover around their revenue maximizing levels. Raising them further will only encourage taxpayers and their capital to leave. That’s not a sustainable path for a state, or a country.
Senate Joins CTA Relief Effort
More good news on the CTA front. Fresh on the heels of the House Financial Services Committee advancing CTA relief, the Senate has stepped up with legislation of its own. Senators John Kennedy (R-LA) and Mike Lee (R-UT) introduced a bill this week that mirrors the House approach, codifying Treasury’s March 2025 rule limiting beneficial ownership information reporting to foreign entities only, while also requiring FinCEN to delete the personal data already collected from American business owners under the original mandate.
It’s a welcome development and a sign that momentum is building on both sides of the Capitol.
The Kennedy-Lee bill takes the same pragmatic, risk-based approach to beneficial ownership enforcement, directing resources toward bad actors rather than treating the entire Main Street business community as a potential suspect. Here’s Senator Kennedy in an accompanying press release:
When an obscure government policy requires small business owners to fork over personal data that even our government admits it doesn’t need, it’s time to change that policy. That’s why I’m leading the bill to permanently end this burdensome mandate and keep law-abiding Americans’ personal information out of a database it should never have been in.
Nine senators were listed as original cosponsors and we’ll be hitting the Hill in the coming weeks to garner additional support.
The path forward in the Senate is not without obstacles. A handful of members on both sides of the aisle continue to view the CTA as a legitimate and legally defensible law enforcement tool. But the reality, as we’ve said before, is the CTA imposes its heaviest burdens on law-abiding Americans while doing essentially nothing to curb illicit activity.
So that means we have work to do. The good news is that the opposition is limited, and the voices cheering this relief are in the millions. We’ll be sharing those stories as we educate lawmakers on the importance of moving this bill and we hope you’ll do the same.
Tax Day Headlines Miss the Full Story
Recent news coverage suggests that the Working Families Tax Cut Act was a bust. Here’s Politico’s Bernie Becker when asked if this tax filing season has lived up to expectations:
The short answer is no… it wasn’t just one person promising $1,000. It was a key line they said over and over again. When you get refunds a third of the way there, there’s no way to suggest anything but that they overpromised.
But the promise of tax savings was not limited to refunds – it also included lower tax payments to close out 2025 and lower taxes paid through withholding or estimated payments for tax year 2026.
Piper Sandler has the full story. Tax refunds have increased by $37 billion and are on track to hit by $50 billion by early May. Non-withheld tax payments have already been cut by $37 billion and are on track to be cut by about $45 to $50 billion. Lastly, reduced withheld taxes should reduce taxes by another $30 billion.

All in, that’s about $130 billion in total relief. That relief is a key component to keeping Main Street humming. As our Main Street Employers Coalition letter signed by 100 trades stated:
Absent action, employers and workers would have faced the single largest tax increase in the nation’s history. This tax hike would have fallen disproportionately on the 95 percent of American businesses organized as pass-through entities – S corporations, partnerships, and sole proprietorships. These businesses employ 63 percent of private sector workers and they contribute the majority of business income to our national economy.
This discussion underscores a broader challenge. If the tax press is struggling to capture how tax relief is actually delivered, it’s no surprise that the public conversation ends up confused. That makes it all the more imperative for Main Street to get out there and tell the full story, something we’re working to do through our Main Street Employers Coalition.
Bottom line: Tax relief is reaching households and Main Street businesses through multiple channels, and any serious assessment should account for all of them.
House Panel Moves CTA Relief
As we previewed recently, the House Financial Services Committee yesterday advanced legislation that would repeal the Corporate Transparency Act’s reporting requirements for over 30 million American businesses. The measure – as amended and approved by the panel – codifies a Treasury Department rule limiting the CTA’s scope only to foreign entities, while protecting sensitive information already collected under the state by requiring a purge of the beneficial ownership database.
It’s a huge win for the tens of millions of Main Street businesses targeted by this ill-conceived reporting regime, and marks a new milestone in our efforts to rein in one of the most sweeping data collection mandates ever conceived. Better still, it appropriately applies a risk-based approach to enforcement that shines a spotlight on bad actors, not law-abiding Americans.
So why was this action necessary? Here’s the bill’s sponsor, Representative Warren Davidson:
We’ve heard from small businesses and individual citizens from around the country who have been shocked to find that their small business is presumed to have committed a crime. Therefore, they’re essentially being served a search warrant…This is the most poorly thought out, poor structured approach that I could think of.
What we need to do today is lock in the rulemaking that the executive branch has done. They’ve had the notes of proposed rulemaking. They’ve had massive feedback. And the feedback overwhelmingly says that the people want to they want to they want to they want security, but they also want privacy, just like the Founding Fathers did. And that’s why our Constitution’s structured the way that it is. So I think the Administration’s thoughtfully addressed this, and now it’s our burden to do this with lawmaking.
Chairman French Hill later shared his thoughts:
Let’s start out with some basic principles here. First, it is illegal to do money laundering, illegal to structure transactions, illegal to hide money through the American corporate system. And we have a rule on that that’s been in place since 2016, the Customer Due Diligence rule, where every bank already collects the beneficial ownership information for everyone who has a business entity in the company.
Second, the impact on the small business community: 33 million businesses have to comply with the rule as designed…we’re asking Joe’s HVAC company to go through the process of complying with a form with a government entity he’s never heard of, filling out another form that could be a database that could be leaked. As passed by Congress, this act imposed an onerous, confusing, duplicative filing requirement on small businesses.
If we limit the beneficial ownership database to foreign actors… aren’t we marshaling our resources directly at the people we suspect of tax evasion or human trafficking or money laundering? I think it better focuses federal resources, and I think it’s more fair to our small businesses.
Longtime S-Corp ally Carol Roth also weighed in to urge lawmakers to advance the measure:
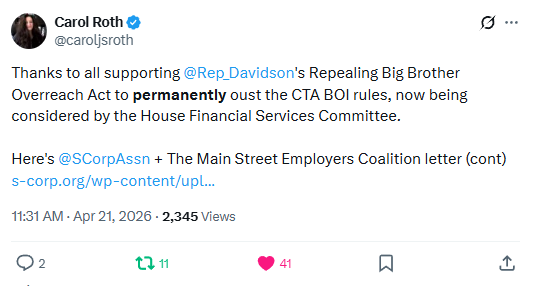 In short, today’s markup reflects that sustained advocacy and a growing recognition in Congress that the CTA’s reporting regime misses the mark.
The bill now heads to the House floor, where lawmakers will have another opportunity to deliver meaningful relief to Main Street while preserving the tools needed to combat illicit finance. We’ll be urging lawmakers to act swiftly and hope you’ll join our efforts.